Biofuels like renewable diesel can already replace up to 100% of the diesel in a tank, while most biodiesel blends stop at B20, or 20% biodiesel. Ethanol works completely differently from both, made by fermenting starch or sugar instead of processing fat and oil.
Your vehicle and your state decide which of the three you end up pumping. One federal tax credit behind these fuels alone is projected to cost $25.7 billion through 2029, money that moves through fuel prices before it reaches your tank.
How each fuel gets made
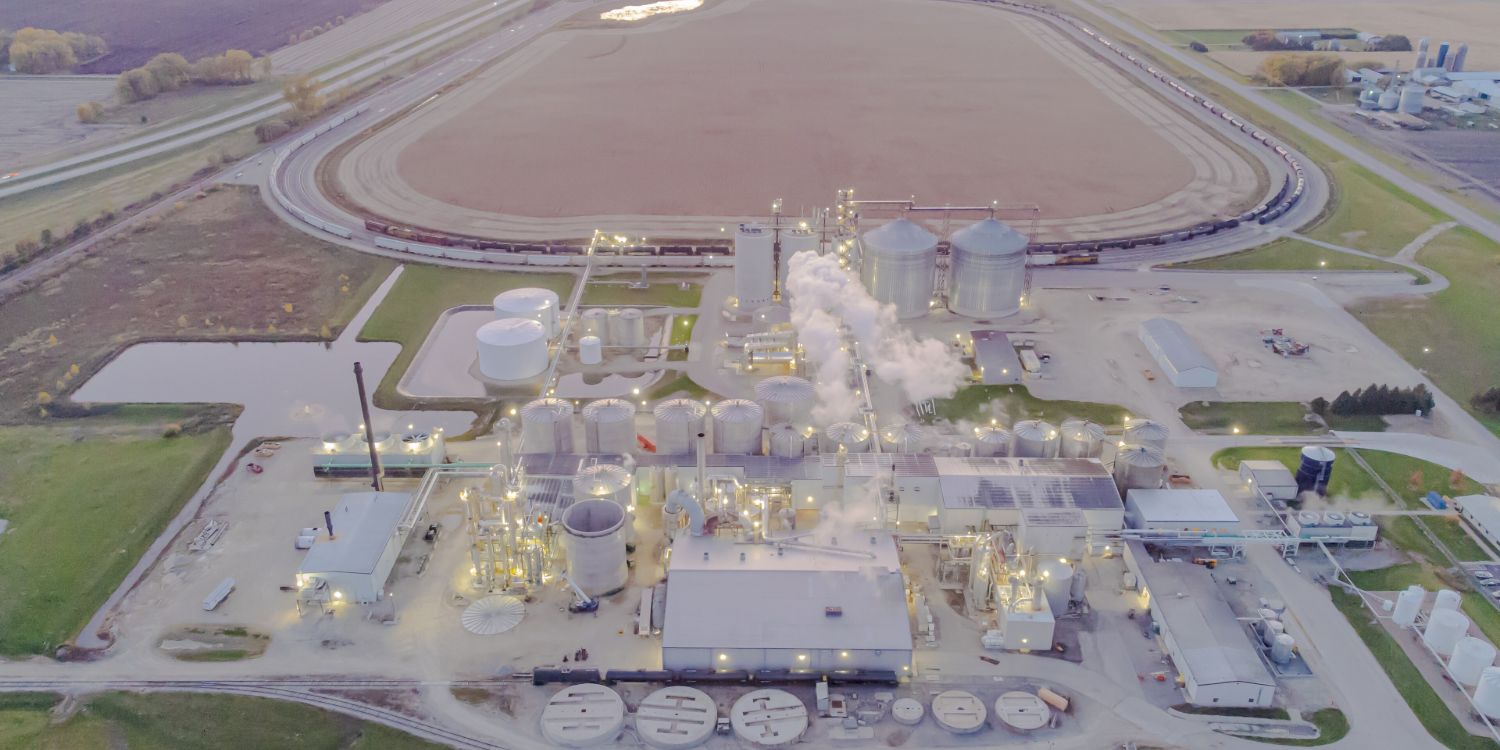
Ethanol is grain alcohol. Producers use yeast to ferment the starch or sugar in corn or sugarcane, then distill the result up to fuel grade and add a denaturant so it can’t be sold as a beverage before it’s blended into gasoline, as the Energy Information Administration explains. It’s the same basic biology as a distillery, aimed at your gas tank instead of a bottle.
Biodiesel takes a different chemical path, called transesterification. A producer mixes roughly 100 pounds of oil with 10 pounds of methanol, using a catalyst such as sodium or potassium hydroxide. That reaction yields 100 pounds of biodiesel and 10 pounds of glycerin, according to the Department of Energy’s Alternative Fuels Data Center.
That glycerin isn’t waste. It’s sold into pharmaceutical and cosmetics manufacturing.
Renewable diesel skips transesterification. Refiners run the same fats and oils through hydrotreating, adding hydrogen under heat and pressure to strip out oxygen and produce what the industry calls hydroprocessed esters and fatty acids, or HEFA. The output is a hydrocarbon chain almost indistinguishable from petroleum diesel, so it meets ASTM D975, the petroleum diesel spec, instead of the separate ASTM D6751 standard written for biodiesel, per EIA.
What feeds the vats and reactors
Corn is the dominant US ethanol feedstock, and it’s likely to stay that way. Cellulosic ethanol made from non-food plant material such as corn stover or switchgrass is technically feasible, but as of the end of 2022 the country had no commercial cellulosic ethanol production running at all, per EIA.
Biodiesel and renewable diesel draw on a more overlapping feedstock pool, led in the US by soybean oil, with animal fats and used cooking oil or yellow grease from restaurants filling out most of the rest, and rapeseed and palm oil more common abroad, according to EIA. The soybean oil in your kitchen pantry and the soybean oil headed to a renewable diesel plant come out of the same crush, competing for the same crop.
From the operations side, feedstock cost is the line that decides whether a renewable diesel plant turns a profit in a given quarter, since soybean oil and used cooking oil trade in commodity and export markets that move for reasons that have nothing to do with fuel policy.
How much of each you can put in a tank
| Fuel | Common blends | Blending limit |
|---|---|---|
| Ethanol | E10, E15, E85 | Roughly a 10% average blend wall across the gasoline pool |
| Biodiesel | B2, B5, B20, B100 | Many vehicle warranties cap it around B20 |
| Renewable diesel | R20 through R100 | None. It’s a true drop-in fuel |
Source: EIA and the Department of Energy’s Alternative Fuels Data Center.
Nearly all US gasoline is sold as E10, a 10% ethanol and 90% gasoline blend. E15, approved for cars from model year 2001 onward, runs up to 15% ethanol, so if your car is that age or newer, you can likely use it. E85 goes further, at 51% to 83% ethanol, but it needs a flex-fuel vehicle and is sold at roughly 4,300 stations, mostly in the Midwest, per EIA.
The “blend wall” describes the point where the national gasoline supply can’t absorb more ethanol without pushing the average blend rate above 10%, per EIA. Ethanol’s share of gasoline consumption first cleared 10% in 2017, according to that same page, and hit a record 10.38% in 2022, per the Renewable Fuels Association. The trade group put 2023 ethanol use 634 million gallons above that ceiling.
Biodiesel usually shows up as B2 or B5 at the pump. B20 is common in fleet contracts, where most diesel engine makers approve its use, so if you’re driving a standard diesel pickup, B20 usually fits inside warranty, though B100 needs equipment built to run on it.
Renewable diesel faces no such ceiling. It’s chemically similar enough to petroleum diesel to run at full strength or blend at any ratio, without the warranty limits that cap biodiesel at B20.
The federal program that created this market
Almost none of this scale would exist without the Renewable Fuel Standard. Refiners and importers, the program’s “obligated parties,” must retire enough Renewable Identification Numbers, or RINs, to meet an annual quota, with one RIN standing in for one ethanol-equivalent gallon, per EPA.
Each RIN also carries a D-code that marks its feedstock and the emissions cut it has to clear. Conventional biofuel like corn ethanol carries a D6 code and a 20% required cut. Advanced biofuel is D5 and biomass-based diesel is D4, each needing a 50% cut, while cellulosic biofuel is D3 at a 60% cut, per EPA.
EPA finalized the 2026 and 2027 volume requirements on March 27, 2026, setting total renewable fuel obligations at 26.81 billion RINs for 2026 and 27.02 billion for 2027, with biomass-based diesel alone set at 9.07 billion for 2026, per the agency’s final rule. Part of that jump reflects reallocated small refinery exemptions from 2023 through 2025.
The market noticed. By June 4, 2026, the D4 biomass-based diesel RIN traded at $2.41 a gallon and the D6 ethanol RIN at $2.37, both near 2021’s all-time highs and roughly double where they started the year, per EIA. EIA expects ethanol production to rise about 2% in 2026 from 2025, with renewable diesel output climbing about 24% and biodiesel about 41% over the same span. Refiners’ RIN costs never show up as a line item on your receipt, but they get built into what you pay for fuel at the pump.
California’s carbon math, and the credit that replaced it
California runs its own carbon-pricing system on top of the federal one. Its Low Carbon Fuel Standard, or LCFS, sets a declining carbon-intensity benchmark for transportation fuel sold in the state, and fuel scoring below the benchmark earns credits sold to fuel scoring above it, per CARB. Tighter benchmarks took effect July 1, 2025, splitting the year into two compliance periods, per CARB’s FAQ. Biodiesel and renewable diesel both earn LCFS credits when they beat the benchmark, and that value stacked on federal RIN value often makes a West Coast renewable diesel plant pencil out.
If you fill up in California, part of what you pay already reflects this credit trading, layered on top of the federal RIN price covered above.
A newer federal tax credit reshaped the incentive further. The Clean Fuel Production Credit, known as 45Z, replaced older, separate blender credits for biodiesel and sustainable aviation fuel with one production-side credit, effective for fuel produced starting January 1, 2025, per the American Farm Bureau Federation. It pays 20 cents a gallon at the base rate, scaling up to $1 a gallon for fuel that cuts emissions the most under the Department of Energy’s GREET model.
Congress’s 2025 reconciliation law, the One Big Beautiful Bill Act, extended 45Z through 2029 and excluded indirect land-use-change emissions, or ILUC, from the carbon-intensity math. That change lowers the scored emissions for corn ethanol and soy biodiesel by 20 to 25 grams of CO2-equivalent per megajoule, per the Clean Air Task Force.
The same law cut the SAF credit from $1.75 a gallon to the same $1 cap as other biofuels, a 43% reduction, and it now restricts qualifying feedstock to North America. The Joint Committee on Taxation now estimates the credit will cost $25.7 billion through 2029, up from its original estimate near $2.9 billion for the four-year version.
Sustainable aviation fuel is next
Sustainable aviation fuel, or SAF, mostly runs through the same HEFA hydrotreating process as renewable diesel, finished to jet fuel specifications instead of diesel. US SAF production capacity sat at around 2,000 barrels a day at the start of 2024, spread across two plants, per EIA.
Capacity built fast. Phillips 66’s Rodeo, California refinery began producing about 10,000 barrels a day of SAF by mid-2024, and Diamond Green Diesel’s Port Arthur, Texas plant reached about 15,000 barrels a day by the end of 2024, per EIA. By May 2025, total US SAF capacity had grown to around 30,000 barrels a day.
Even at that pace, SAF is expected to stay under 2% of the 1.7 million barrels a day of US jet fuel consumed through 2025 and 2026, per EIA. Your seat on a US flight is still burning almost entirely petroleum jet fuel for now. Feedstock is what caps SAF’s growth. It draws on the same limited pool of waste fats and vegetable oil that biodiesel and renewable diesel use, and it competes with both for the same 45Z credit.
Your grocery bill and your gas tank pull from the same soybean field
Rising mandates mean rising demand for feedstock that also feeds people and livestock. US biomass-based diesel output hit a record 4.86 billion gallons in 2024, and the American Soybean Association expects actual 2026 production near 5.86 billion gallons once EPA’s small-refinery-exemption reallocations are counted in.
That’s the case producers and farm groups make for expanding the mandates. Critics look at the same numbers and see cropland getting redirected toward fuel instead of food. That overlap in supply is why a tighter feedstock market can move what you pay for groceries about as easily as it moves what you pay for fuel.
The 45Z exclusion of ILUC sharpens that fight, since it doesn’t change what happens on the ground if farmland devoted to fuel pushes crop production onto land that would otherwise stay in pasture or forest, a version of the same carbon-accounting debate that surrounds biomass. Producers counter that the old ILUC penalty rested on modeling assumptions rather than a measured outcome, and neither side has new data that changes the other’s mind.
What’s certain is the volume. US biomass-based diesel production is on pace to climb from that 2024 record toward 5.86 billion gallons in 2026, gallons that have to come from the same soybean oil and used cooking oil supply that also fills a shopping cart.