Originally published March 12, 2015. Updated July 23, 2026.
The smart grid is today’s power grid with two-way digital communication built into it, and by 2022, 72% of US electric meters could already report your usage automatically instead of waiting for a monthly read. The bigger change is what utilities do with that connection. They pay you to shift your usage instead of building another plant, and they’re rethinking how they get paid for running the grid at all.
Smart meters went from rare to the norm
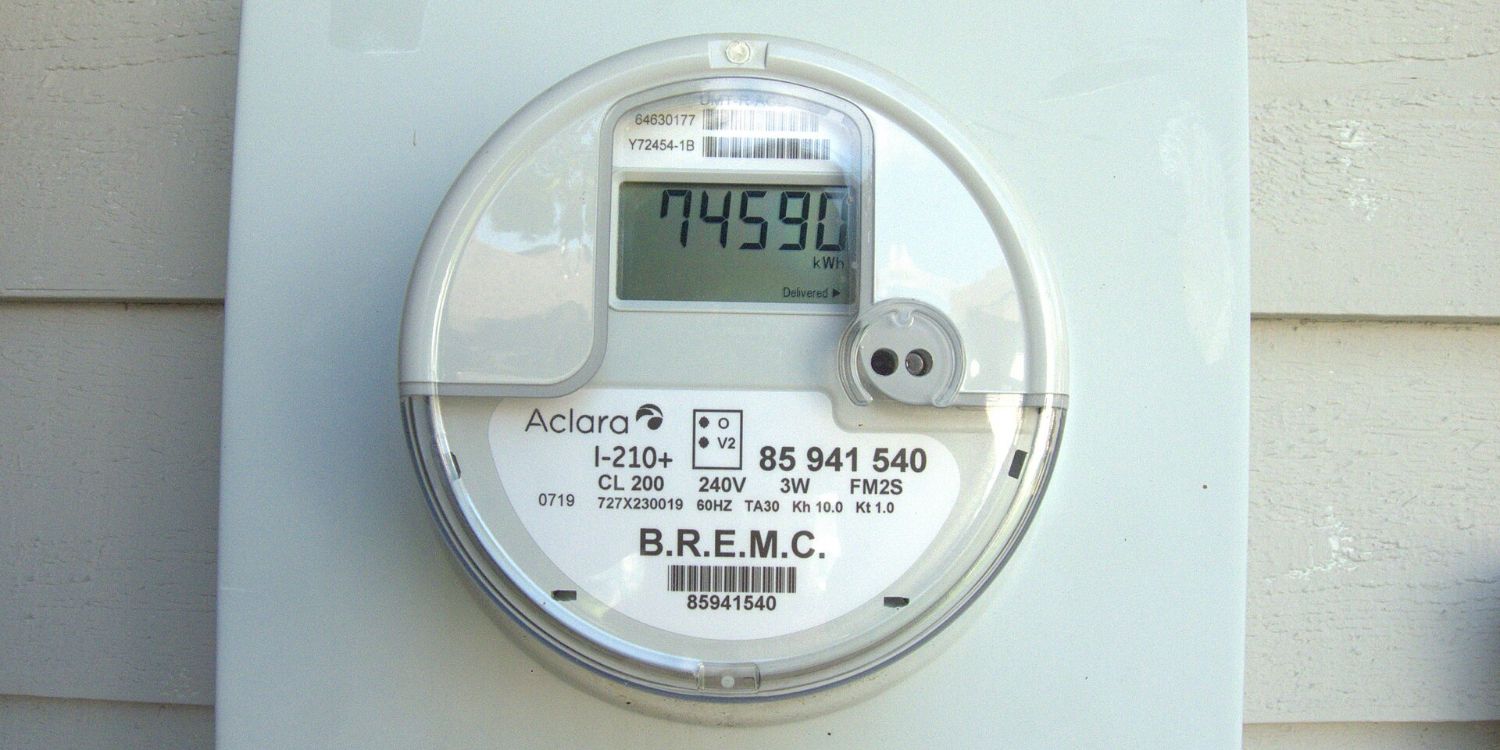
A smart meter is the box on the side of your house, upgraded to send usage data back automatically instead of waiting for a meter reader to check the dial by hand. That upgrade used to be rare. The trend by year:
| Year | Smart meters installed | Share of all US meters |
|---|---|---|
| 2016 | 71 million | 47% |
| 2019 | 94.8 million | 60.5% |
| 2022 | 119 million | 72% |
Source: EIA, Today in Energy, EIA, Electric Power Annual Table 10.10, EIA FAQ #108.
The pool of meters those shares are measured against grew too, from about 150 million total US meters in 2016 to 156.6 million by 2019, so the smart share climbed on top of a bigger base of meters each year.
On homes specifically, the 2022 share is a bit higher. 73% of residential meters are smart meters, the number that feeds directly into the rates and programs covered next.
What demand response and virtual power plants pay you for
Demand response is a grid operator paying you, or your smart thermostat, to use less power for an hour instead of firing up an expensive plant to cover it. Grid operators buy that promise of available capacity much like they buy capacity from power plants. Retail and wholesale demand response programs combined could cut roughly 63 GW at peak, based on FERC’s most recent tally, which draws on 2022 and 2023 filings. The wholesale piece, run mostly by regional grid operators instead of individual utilities, covers about 6.5% of wholesale peak demand on its own. On the customer side, about 10.3 million customers were enrolled in incentive-based retail demand response programs in 2022, a slight dip from the year before.
A virtual power plant is the newer, more automated version of the same idea. Instead of one utility program, thousands of home batteries and smart thermostats get pooled together and dispatched like a single plant. The Department of Energy wants to triple that kind of capacity by 2030, a move it estimates could save the grid $10 billion a year. Reporting on that plan puts today’s pooled fleet at 30 to 60 GW, growing to a 2030 target of 80 to 160 GW, enough to cover 10% to 20% of US peak demand.
Time-of-use rates finally caught up with the meters
Time-of-use and other dynamic electricity rates charge different prices depending on when you use power, cheaper overnight, pricier during the evening peak. FERC counted 15.6 million US customers enrolled in dynamic or time-varying pricing programs in 2022, up 6.5% from the year before. Time-of-use plans are the largest slice of that group, but the total also folds in critical-peak pricing and real-time pricing, among other variants, so not every one of those 15.6 million customers sits on a strict time-of-use plan. For a household using the average 10,791 kilowatt-hours a year, when you run the dishwasher can now matter almost as much as how much you run it.
What New York’s Reforming the Energy Vision built
New York’s version of all this predates most of it. In a March 2015 analysis for the Environmental Defense Fund, attorney Elizabeth Stein described the state’s newly issued “Track One” order in its Reforming the Energy Vision proceeding, which had set up utilities as “Distributed System Platform” operators on Feb. 26, 2015, running a technology and market platform where outside companies would compete to sell demand response, efficiency, storage and solar instead of the utility owning it all. That platform role covered planning the system and running the grid day to day, plus running the new markets for those outside providers. New York’s Public Service Commission kept utilities from owning most of those resources themselves, modeling the split on how regional grid operators are kept separate from owning power plants in wholesale markets, to avoid a conflict of interest. A second order in May 2016 filled in how utilities would get paid for that role, a new Value of Distributed Energy Resources tariff, or VDER, that replaced net metering.
A decade on, REV has real wins and real shortfalls attached to it. New York became the #1 US community solar market by 2020, a result analysts partly credit to VDER, and Con Edison’s Brooklyn-Queens Demand Management program used non-wires alternatives, paying for demand response and storage instead of building new wires, to defer a $1.2 billion substation upgrade. On the other side of the ledger, by late 2021 the Distributed System Platform concept had advanced only partially, and the earnings adjustments meant to reward utilities for running it well were inconsistent from one rate case to the next.
Utility business models are changing beyond New York
New York didn’t invent this pressure. Every rooftop solar panel or home battery a customer installs is capacity the utility didn’t build and doesn’t own. REV’s answer, described above, was to give the utility an official role in planning around that equipment and running the market for services built on top of it, instead of leaving each utility to work it out program by program on its own.
Utilities and regulators have argued over distributed generation and utility disintermediation for a decade, before REV and after it. Utilities are moving from building wires and billing by the kilowatt-hour toward planning around equipment they don’t own and running a market for what gets built on top of it.
What would move these numbers next
The clearest number to watch is the Department of Energy’s target of tripling virtual power plant capacity by 2030, moving today’s pooled fleet of 30 to 60 GW up to a range of 80 to 160 GW. If that happens on schedule, virtual power plants alone would cover an estimated 10% to 20% of US peak demand.
The smart meter count is also due for an update. EIA’s page carrying the 119 million figure was last updated in October 2023, so any meters installed after that aren’t counted in the 72% figure yet. New York’s own numbers are still being tested rate case by rate case. The next real signal on REV is whether the earnings adjustments meant to reward utilities become more consistent than the partial record Utility Dive found through 2021.
